Building and house and land
Construction Loans Coffs Harbour
A lender prices your build off the finished house, not off the contract. So if the construction loans Coffs Harbour builders quote you run above what the completed house will value at, the difference comes out of your deposit.
We read the building contract before you sign it, split the land and the build so the drawdowns work, and confirm whether the project unlocks the $10,000 grant.
- Building contract read against lender policy first
- Progress draws lodged and chased at every stage
- Combined land and build figure checked against the grant cap
Have your build checked
The draft contract, the land price and your income are enough to look at.
What We Do For People Building
We arrange the finance for a house that does not exist yet. That means reading your building contract against what lenders will accept, structuring the land and the build as one funding package, getting it approved against the end value, and then running the progress draws so your builder is not standing on site waiting for a bank.
It covers both of the usual shapes: a house and land package bought together, or a knockdown rebuild on a block you already hold in Coffs Harbour. Both draw down in stages, and both need a fixed price contract for the lender to value against.
Reading a draft contract and telling you whether it will finance costs you nothing, even if you then decide not to build. We are paid a commission by the lender when a loan settles, so the review that talks you out of a contract is the one we are not paid for.
The best time to talk to us is before you sign the building contract, because that document sets the terms the finance has to live inside. After you have signed is still workable. It is just a smaller set of options.
Step by step
What We Do At Each Stage Of Your Build
Construction finance has more moving parts than a purchase does. We hold the lender end of every one of them.
-
Contract review
Before you sign. We read the building contract against lender requirements and flag whatever will cause trouble at valuation or at drawdown.
-
Structuring land and build
A few days. We split the finance so the land settles cleanly with the build funds behind it, and check the combined figure against the grant caps.
-
Approval and land settlement
Usually four to six weeks. Full assessment on the end value, then settlement on the land so your builder can get started.
-
Progress draws
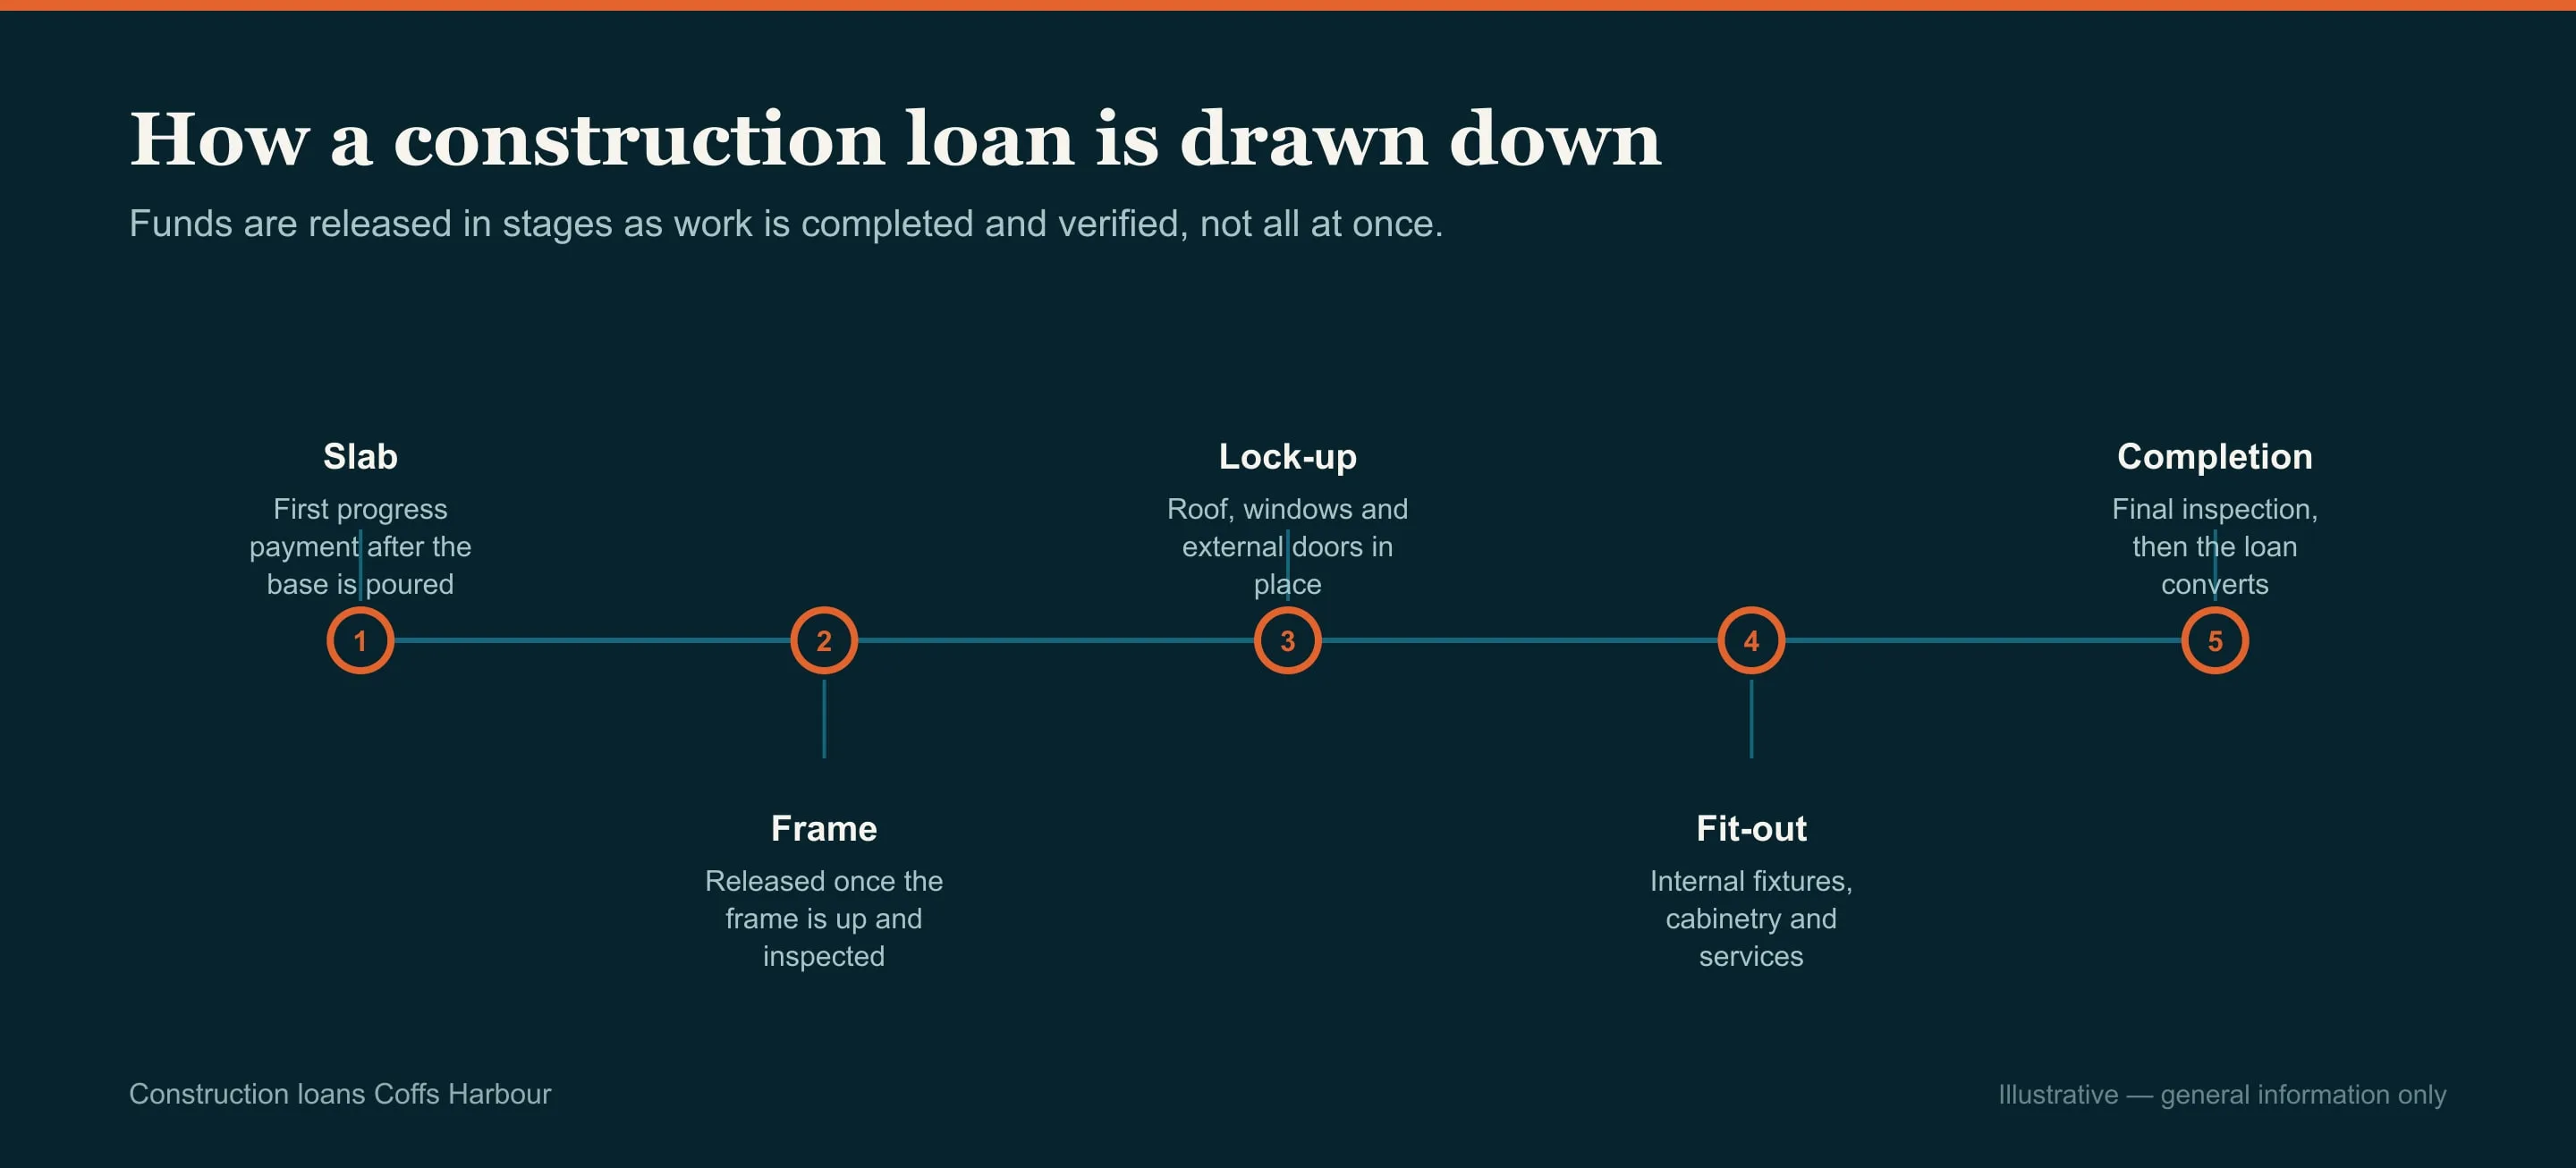
Through the build, five stages in most contracts. We lodge each claim, chase the inspection and get the funds released so the site keeps moving.
-
Completion
Final inspection, final draw, and the loan converts to normal principal and interest repayments on the full balance.
What to have ready
- The fixed price building contract and the plans, if you have them yet
- The land contract, or your rates notice if you already own the block
- Payslips or tax returns for every applicant
- Evidence of your savings and any contingency funds you are holding
First questions
What People Ask Before They Build
What does the finance work cost me?
Nothing, and a construction file takes considerably more managing than a purchase does. The lender pays us a commission when the loan settles, so reviewing a draft building contract and telling you whether it will finance costs you nothing even if you then decide not to build. Where a fee could apply we tell you the amount in writing first.
What do you need from me before I sign a building contract?
The draft contract, the plans and a rough figure for the land. That is enough for us to tell you whether it will finance and whether it clears the grant cap while you can still change something, which is the whole point of doing it at this stage.
Can I talk to you before I have chosen a builder?
Yes, and it is a good time to do it. What you can borrow sets the contract price you can sign, so knowing the number first stops you designing a house the finance will not reach. We can also tell you what lenders think of the contract types your shortlisted builders use.
Building A New Home in Coffs Harbour
The first thing we look at is your building contract, because the finance is built on top of it. A fixed price contract from a licensed builder is what most lenders want to see: it fixes the number they are valuing against and caps their exposure to cost blowouts.
Cost plus contracts and owner builder projects are harder to finance in Coffs Harbour, and a much shorter list of lenders will look at them. Not impossible, but it changes the deposit you need and the evidence we have to assemble. Tell us which one you are heading toward in the first conversation.
PRD’s first quarter 2026 report describes a residential pipeline here dominated by vacant land lots rather than completed homes. More of the stock coming to market in Coffs Harbour therefore needs construction finance rather than a standard home loan, and it is worth knowing which one you are shopping for before you talk to a bank.
How Progress Payments Work
Your lender does not hand over the full amount at settlement. It releases funds in stages as the build reaches them, and you pay interest only on what has been drawn. Repayments therefore start small and climb as your Coffs Harbour house goes up.
The usual stages are slab, frame, lock up, fixing and completion, and Coffs Harbour builders will invoice against them in that order. Each draw needs the builder’s invoice and, at most stages, an inspection. We run that cycle for you: chasing the valuer, submitting the claim, pushing the release through.
What the lender is valuing
The valuation is done on completion. It is an assessment of what the finished Coffs Harbour house will be worth, measured against the fixed price contract and the plans. If the contract price sits above what the finished product will value at, the shortfall comes out of your deposit, and we would rather flag that before you sign than at stage three.
Most lenders also want genuine savings and a contingency margin on top of the contract price, for variations and the things that always come up. We build that into the numbers from the start so it is not a surprise later.
Combined cap for the new-home grant
$750,000 land and build
Land plus build has to come in at or under this to qualify. A completed new home bought outright is capped lower, at $600,000. Established homes never qualify at all.
Revenue NSW, First Home Owner Grant (New Homes)
Your $10,000 Grant Eligibility
The First Home Owner Grant is worth $10,000, and it is the one piece of assistance that building in Coffs Harbour unlocks and buying established does not. It has value caps, and which cap applies depends on how you are buying.
| How you are buying | The cap that applies |
|---|---|
| Buying a completed new home | Value of $600,000 or under |
| Buying land and building on it | Land and build combined at $750,000 or under |
| Buying an established home | Never eligible, at any price |
We check your contract against whichever of those applies before you sign, because a combined figure landing just over the cap costs you the whole grant rather than part of it. Where it is close, it is sometimes worth looking again at what sits inside the build contract and what sits outside it.
One rule that works in your favour
New dwelling construction loans are exempt from APRA’s debt to income cap, the limit restricting lenders to no more than 20% of new mortgages at six times income or above from February 2026. If your income multiple is high, building may be approvable where buying established would not be, and we check whether that exemption applies to you.
House And Land Finance in Coffs Harbour
A house and land package is two transactions financed as one. The land settles first on a normal settlement, then the build draws down in stages behind it. Getting that split right is what keeps the combined figure under the grant cap and the end value loan to value ratio where the lender wants it.
We structure your Coffs Harbour package so the land settlement does not use up capacity you need for the build, and so the two contracts read consistently to a credit assessor. Packages sold as a single price sometimes need unpicking before a lender will look at them, and that is much better done before you exchange.
If the block runs over about a hectare, or the land is rural zoned, the lender list narrows for reasons that have nothing to do with the build itself. Plenty of blocks in the hills behind Coffs Harbour fall into that category, so say so early and we will take it into account when we choose where to lodge.
Asked and answered
Questions About Building
Do I still get the $10,000 grant if I build?
Yes, provided you are a first home buyer and the value comes in under the cap: $750,000 for land and build combined, or $600,000 for a completed new home. We check your contract against whichever figure applies before you sign.
How do progress payments work?
Your lender releases funds in stages as the build reaches them, commonly slab, frame, lock up, fixing and completion. You pay interest only on what has been drawn, so repayments start low and rise as the house goes up. We lodge each claim and chase the release.
Is the loan assessed on the land or the finished house?
On the finished house. The valuation is done on completion, against your fixed price contract and the plans. If the contract price sits above the likely end value, the gap comes out of your deposit, which is why we look at it before you commit.
Can owner builders get finance?
Some lenders will, on tighter terms and a larger deposit, and the list is short. You will need your owner builder permit, a detailed costing and usually more of your own money in the deal. Tell us early and we go straight to the lenders that entertain it.
Who you deal with
Who You Will Be Dealing With
Builds run long, and the useful thing about one broker holding the file is that nobody has to be brought up to speed at stage four. The person who read your contract in January is the person lodging your lock up claim in July.
We are in Coffs Harbour and used to working alongside local builders and their schedules, which mostly means answering the phone when a claim needs to go in before the end of the week.
- What it costs to ask
- Nothing. Reviewing your build and the finance is free, and the lender pays us on settlement.
Where to start
Have It Checked Before You Sign
A contract reviewed before signing is worth far more than one reviewed after. Send through the draft, the land price and your income, or call and we will talk it through first.