Retirement income, exit strategies, super
Downsizing Home Loans Coffs Harbour
Being knocked back at 62 is almost never about your age. Downsizing home loans Coffs Harbour lenders turn down are refused on capacity, and unlike your age, capacity is something we can document.
We build the exit strategy a lender needs to see, evidence the income and assets behind it, and structure the loan around when you actually plan to stop working.
- An exit strategy written for the lender, not implied
- Retirement income evidenced properly
- Loan term matched to your plans, not to a template
Talk through a downsize
A rough idea of what you would sell, what you would buy, and when.
What We Prepare On Your Behalf
We review what you will be living on: superannuation, a pension entitlement, ongoing work, rent, and any assets you plan to sell. Then we write the exit strategy that shows how the loan gets repaid, evidence it, and take it to a lender whose policy accepts that kind of strategy for a Coffs Harbour property. It is a documentation job more than a credit one.
It suits you if you are selling a larger home in Coffs Harbour and buying something smaller with a shortfall to cover, if you are borrowing into or near retirement, or if the bank has already asked you a question about your age and you did not know how to answer it.
The conversation costs you nothing. We are paid a commission by the lender when a loan settles, so working out that you do not need to borrow at all, which happens reasonably often on a downsize, costs you nothing either.
Step by step
How We Structure A Downsizing Loan
Four stages. The exit strategy is the one that decides the outcome on a Coffs Harbour downsize, so it is built first rather than added when a lender asks.
-
Retirement income review
We go through what you will be living on and when that changes. If you intend to stop working in three years, the loan has to make sense in year four, and that is the test the lender applies.
-
Exit strategy documentation
We write out how the loan is repaid and attach the evidence: super statements, a valuation, a contract, whatever the strategy rests on. An unevidenced strategy is the same as no strategy to a credit assessor.
-
Lender match
Lenders differ on which exit strategies they accept and how far past retirement they will lend on a Coffs Harbour property. We put your file to one that accepts yours instead of hoping.
-
Application and settlement
We lodge, handle the questions, and coordinate the sale and purchase settlements so the two line up. You are told where it is up to rather than having to ask.
What to have ready
- Your most recent superannuation statements
- Details of any pension or Centrelink entitlement
- Payslips or returns if you are still working, and when you intend to stop
- A rough sale figure for your current home and a budget for the next one
- Statements for any loans or cards still running
First questions
Questions Before You Downsize
What do you need from me to start?
Your super statements, details of any pension, an idea of what your current Coffs Harbour home would sell for and what you would be buying. If you are still working, payslips and roughly when you intend to stop.
Do you charge me for the advice?
No. The lender pays us a commission when a loan settles. On a downsize the answer is sometimes that you do not need to borrow at all once the numbers are totalled, and that answer costs you nothing and earns us nothing.
How long does this take to arrange?
One to two weeks to an approval once your documents are together, then four to six weeks to settlement. Where a sale and a purchase have to line up, the timing of the two contracts drives the schedule more than the loan does.
Home Loans For Downsizers in Coffs Harbour
Nearly a quarter of the people around you are in the same position. The ABS 2021 Census put 23.1% of the Coffs Harbour local government area at 65 or over, against roughly 17.7% across New South Wales, so downsizing finance is ordinary business here rather than an edge case.
That matters practically. The lenders who handle older borrowers well, and the exit strategies they accept, are things we deal with regularly rather than look up when asked. A metropolitan broker who sees one of these a year is guessing at the same question.
The shortfall nobody budgets for
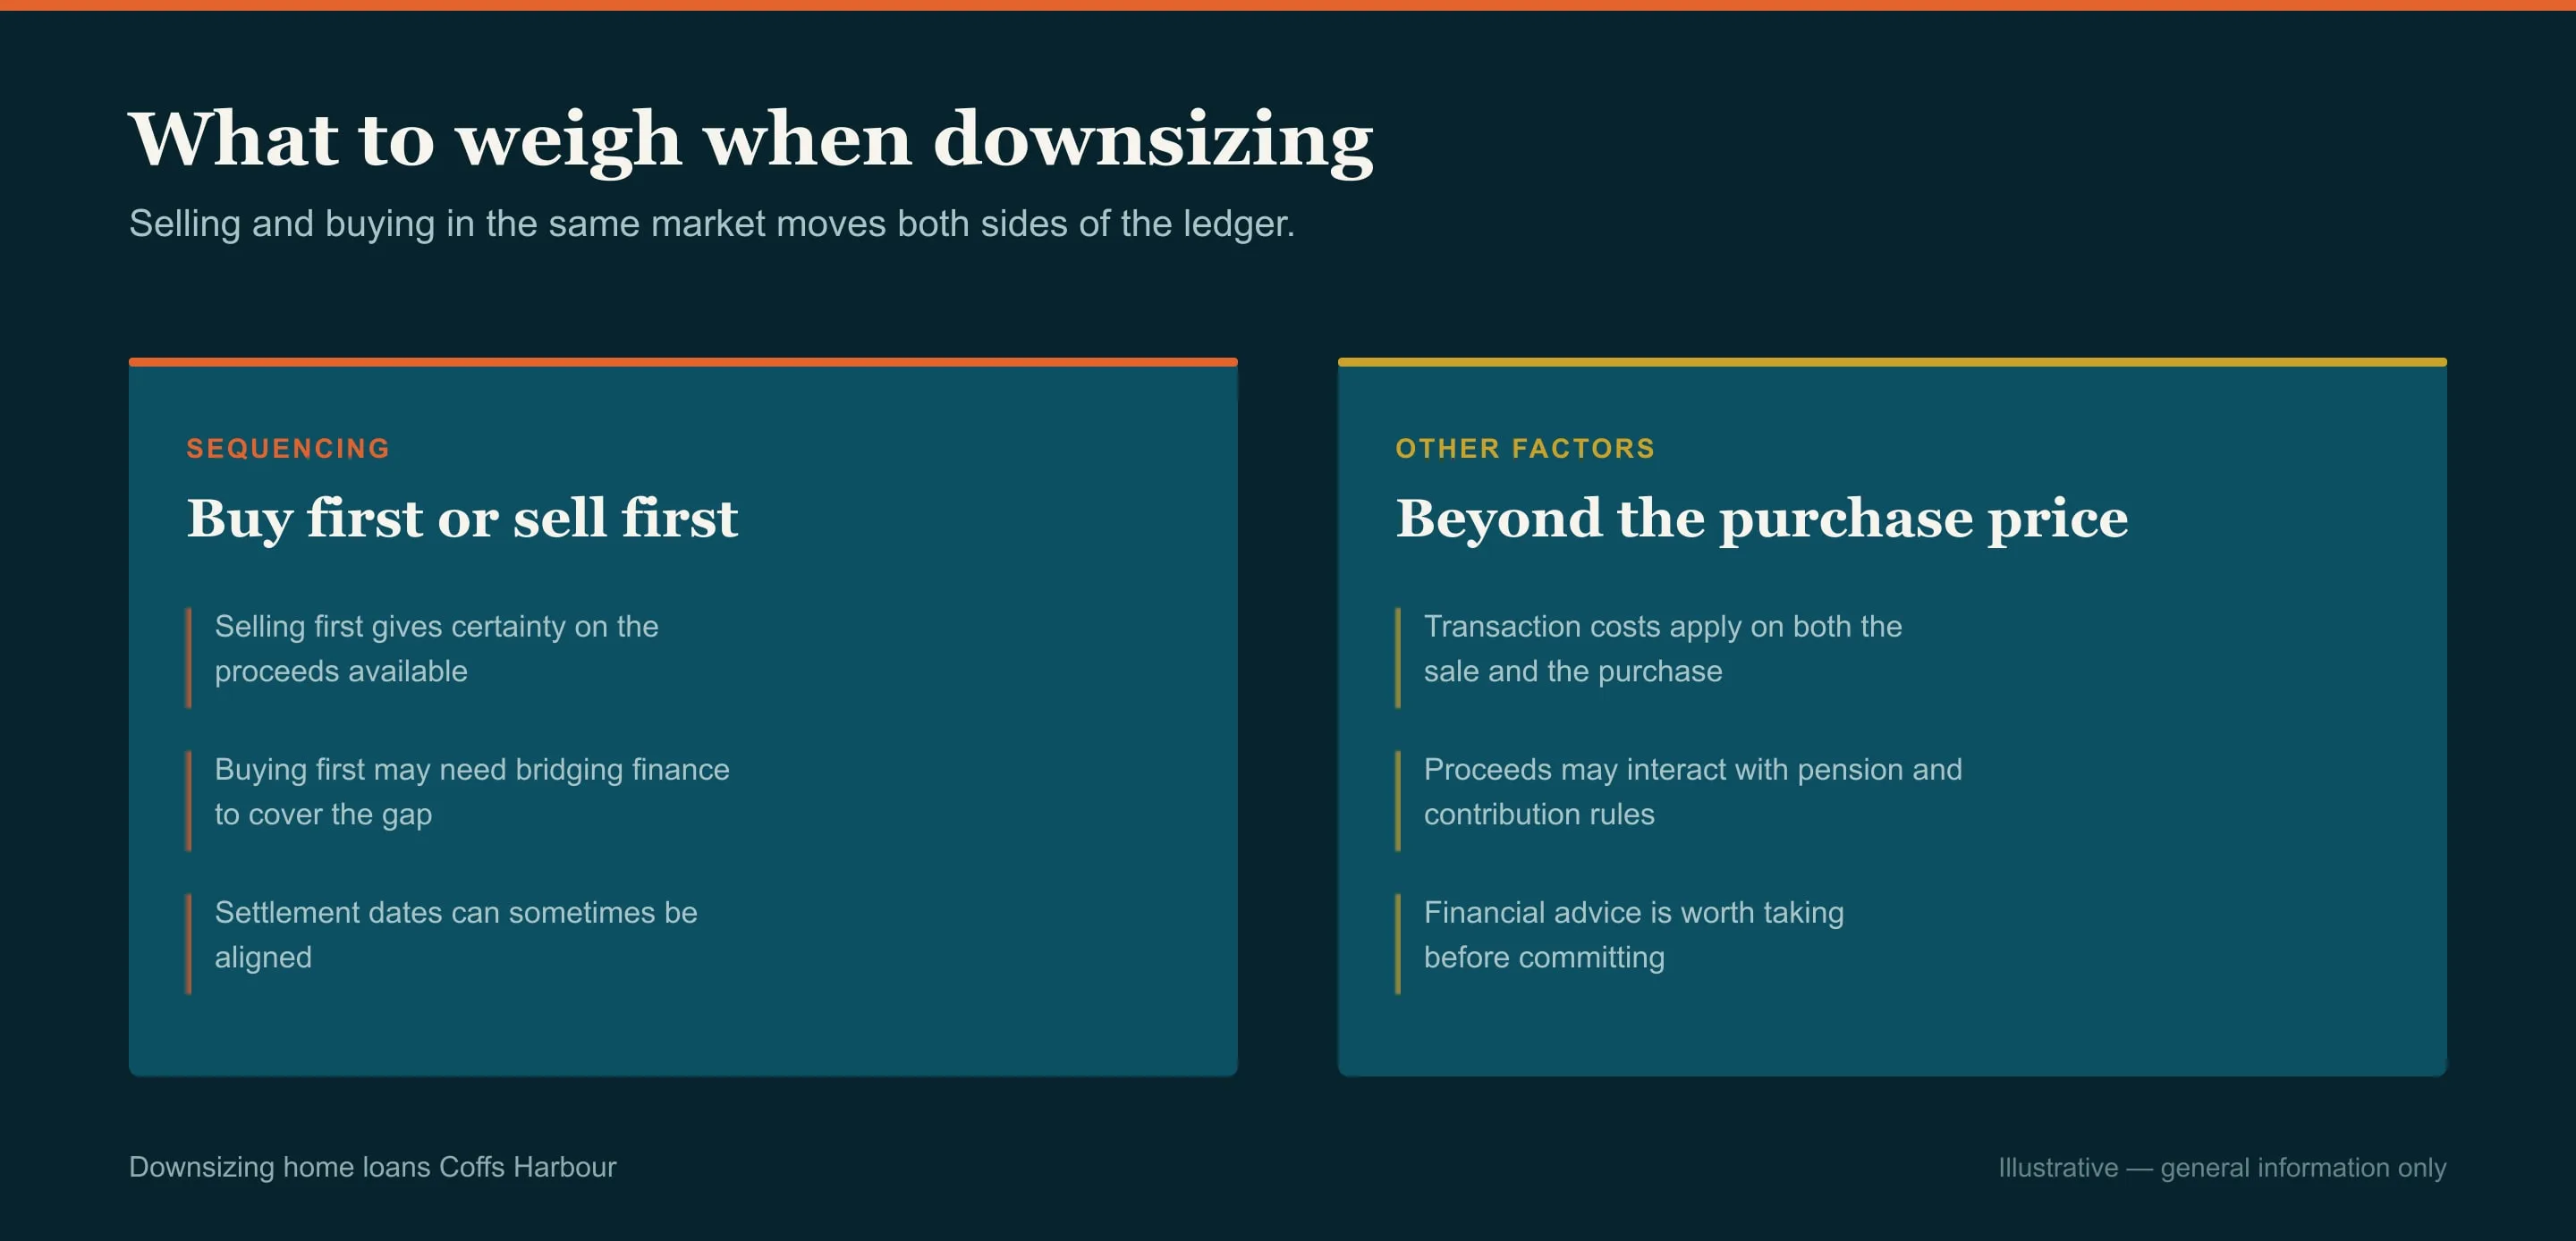
Downsizing in Coffs Harbour rarely releases as much as expected once agent fees, stamp duty on the purchase, moving costs and the gap between the two prices are counted. A smaller home in a better position can cost more than the family home it replaced. We total all of it before you list, so the shortfall is a number you planned for rather than one you meet at contract.
Building The Exit Strategy Lenders Want
An exit strategy is a written, evidenced explanation of how the loan gets repaid once your employment income stops. From around age 55 most lenders require one, and it is a documentation requirement rather than a judgement about you.
What lenders accept
- Downsizing to a lower-value property, with the difference clearing the loan
- Sale of another asset, such as an investment property or a block of land
- A superannuation lump sum, evidenced by current statements
- A loan term short enough that it is repaid before you retire
A strategy relying on selling the home you intend to live in for the rest of your life is the one most often knocked back, because it is not really a plan. We work out which of the accepted strategies you genuinely have and build the file around that one.
How your age is actually treated
Lenders cannot refuse you because of your age. The Age Discrimination Act 2004 prohibits it, and they must instead assess your capacity to repay. What age triggers is the requirement to evidence that capacity beyond the point where you stop working. For a couple, most lenders assess against the older applicant, which surprises people and is worth knowing before you apply.
Downsizer contribution into super
$300,000 each, from age 55
Up to $600,000 for a couple, from the sale of a home owned ten years or more, contributed within 90 days of settlement. Once only, and it sits outside the contribution caps.
ATO Downsizer super contributions, updated 20 January 2026
Putting Home-Sale Money Into Super
The downsizer contribution lets you put up to $300,000 each, or $600,000 for a couple, into superannuation from the sale of your home. It is available from age 55, there is no work test, and you can only do it once.
The conditions that catch people
- You must have owned the home for at least ten years
- The contribution must be made within 90 days of receiving the proceeds
- It is once only, across your lifetime, not once per property
- From age 55, on the ATO guidance updated 20 January 2026
The part most commonly misunderstood: a downsizer contribution does not count towards your contribution caps, but it is included in your total superannuation balance and it does count towards your transfer balance cap. Those are different things and the distinction can change what you should contribute.
We are mortgage brokers, not tax or financial advisers, so we flag where the contribution interacts with your loan timing and tell you to confirm the tax position with the ATO or your adviser. What we do control is the 90 day window, because it runs from settlement and settlement is something we can influence.
Borrowing In Or Near Retirement in Coffs Harbour
You can borrow, and a Coffs Harbour lender assesses the loan on the income you will have rather than the income you have now. Superannuation drawdowns, pension entitlements, rent and part-time earnings all count, provided they are evidenced and provided they continue for the term.
Shorter term, or longer
A shorter term repays before retirement and often removes the exit strategy question, at the cost of a higher repayment now. A longer term is more comfortable monthly and puts the strategy back on the table. Which one suits you turns on when you actually plan to stop working, so we run both terms and put the two repayment figures side by side.
Downsize, or stay and release equity
If the reason for moving is money rather than the house, staying put in the Coffs Harbour home you already own and releasing equity is worth pricing against a sale. Downsizing costs agent fees and stamp duty and gets you out of a home you may not want to leave. Equity release keeps you where you are and adds debt instead. We put the numbers on both, and where equity release is the better fit we explain how that works rather than steering you.
Asked and answered
Downsizing And Retiree Loan Questions
Can I get a mortgage in my 60s?
Yes. Lenders cannot decline you on age under the Age Discrimination Act 2004, and must assess your capacity to repay instead. What changes is that you will be asked for a written exit strategy showing how the loan is repaid after you stop working, with evidence behind it.
What is an exit strategy?
A written explanation, backed by documents, of how the loan gets repaid once your employment income ends. Downsizing, selling another asset, a super lump sum, or a term short enough to finish before retirement are the usual accepted ones. We write it and assemble the evidence as part of the application.
Can I put home-sale proceeds into super?
Through the downsizer contribution, yes: up to $300,000 each or $600,000 per couple, from age 55, on a home owned at least ten years, contributed within 90 days of receiving the proceeds, once only. It does not count towards the contribution caps, but it is included in your total superannuation balance and counts towards your transfer balance cap. Confirm your own position with the ATO or your adviser.
Will the bank use my super to approve me?
Regular drawdowns from super can be counted as income where they are evidenced and will continue. The balance itself is more often used to support an exit strategy than treated as income. Which of the two applies depends on the lender, and it is one of the reasons lender choice matters here.
What happens if my home sells for less than expected?
The shortfall grows and the loan has to cover it, which is exactly why we total the costs and test a lower sale figure before you list. Knowing the number at a price below your expectation is more useful than knowing it at the price you hope for.
Who you deal with
Who Writes Your Exit Strategy
The person who answers is the one who assembles the strategy and the evidence behind it, and who deals with the assessor when a question comes back on it. That continuity matters when a file turns on documentation rather than on numbers.
With 23.1% of the Coffs Harbour local government area aged 65 or over, this is regular work here rather than something looked up for the occasion.
- What it costs to ask
- Nothing. Our commission comes from the lender at settlement, so the advice is free either way.
Where to start
Work Out What A Downsize Leaves You
Tell us what you would sell and what you would buy. We will total the costs, test the shortfall and tell you whether borrowing is needed at all for a move within Coffs Harbour.