Schemes, deposit and duty
First Home Buyer Coffs Harbour
Your First Home Buyer Coffs Harbour price cap is $1,500,000, not the lower rest of state figure quoted in most national coverage, because Coffs Harbour and Grafton are classed together as a regional centre.
We test you against all three assistance schemes, model what each one does to your deposit and your transfer duty, then lodge with a lender that takes part in the ones you can actually use.
- All three schemes checked before you start inspecting
- Deposit, duty and repayments modelled together
- Your postcode confirmed against the regional centre cap
Check which schemes you qualify for
Your deposit, what you earn and what you owe is enough to start.
What We Do For First Home Buyers
We work out which first home buyer schemes you qualify for, then build the loan around the ones you can use. That means testing your eligibility scheme by scheme, modelling what your deposit and your duty look like under each combination, and lodging with a lender that participates in whichever combination you land on. From the first phone call to the day you get the keys, the lender deals with us rather than with you.
It suits you if you are buying your first place in Coffs Harbour and you are at either of the two usual starting points: a deposit saved and no idea what it buys, or a property found and no idea whether it fits a scheme. Both are normal. The first one gives us more to work with.
What the eligibility check costs you
The eligibility work costs you nothing, including the outcome where the answer is no. The lender pays us a commission once a loan settles, so a check across all three schemes against a Coffs Harbour purchase is free whether or not one of them turns out to fit you.
It is not for you if you have held an interest in Australian property before, even a share of one, or if the plan is to rent the place out rather than live in it. Either of those closes off the schemes, though not the loan itself, and we would rather say so in the first ten minutes than three weeks in.
Step by step
What Happens After You Get In Touch
No paperwork in the first conversation. We need enough to give you a straight answer on eligibility, not enough to lodge an application.
-
Eligibility check
Twenty minutes on the phone. Your deposit, your income and your residency status against all three schemes, and a yes or a no on each of them.
-
Scheme mapping
A day or two. We model what every scheme you qualify for does to your deposit, your duty and your repayments, then tell you which combination leaves you in front.
-
Pre-approval
Usually one to two weeks. We package the file and lodge it with a lender that takes part in the scheme you are using, so the answer has been assessed by a person rather than generated by a calculator.
-
Offer support
While you are looking. Every place you get serious about gets checked against the price cap and the likely valuation before you sign anything.
-
Settlement
Commonly four to six weeks from an exchanged contract. We hold the lender, the valuer and your conveyancer to the date and chase whatever stalls.
What to have ready
- Two recent payslips each, plus your last tax return or notice of assessment
- Three months of statements for the account your deposit sits in
- Every loan, credit card and buy now pay later account, showing the limits rather than the balances
- Photo ID, and evidence of residency status if you are not an Australian citizen
First questions
What First Home Buyers Ask Us First
What does it cost me to use you?
Nothing, whether or not you turn out to qualify for a single scheme. The lender pays us a commission once your loan settles, which is how broking works in Australia, so an eligibility check across all three schemes costs you the twenty minutes it takes. If a fee could ever apply to your situation, the amount goes in writing in front of you before you agree to anything.
What do you need from me to get started?
A rough deposit figure, what you and anyone buying with you earn, and your debts listed with their limits rather than their balances. That is enough for a real answer on eligibility. Documents come later, once you have decided to go ahead.
What if I turn out not to be eligible?
Then we tell you what would have to change and roughly how long it takes: a tax return lodged, a credit card limit cut, three more months of savings history behind you. Asking leaves no mark on your credit file, because answering that question does not require a credit enquiry.
Which First Home Buyer Schemes You Qualify For in Coffs Harbour
The three schemes overlap less than you would assume, and in Coffs Harbour you can hold more than one at a time. We test you against each of them before you start inspecting, because the answer decides which listings are worth a Saturday.
The federal 5% Deposit Scheme
Coffs Harbour and Grafton together form a designated NSW regional centre, so the price cap here is $1,500,000 rather than the lower rest of state figure. Both the purchase price and the lender’s own valuation have to sit at or under it, which is why we look at valuation risk on your shortlist before you make an offer rather than after.
From 1 October 2025 the scheme has no place limits and no income caps. Housing Australia’s wording is that any Australian first home buyer with a saved 5% deposit can apply. What that removed was the queue, not the assessment: your lender still has to be satisfied you can repay the loan, and that is the part we prepare for you.
NSW transfer duty relief
The First Home Buyers Assistance Scheme removes transfer duty entirely on a new or existing home up to $800,000, then tapers the concession away to nothing by $1,000,000. On vacant land it is a full exemption to $350,000 and a concession to $450,000. We work out which bracket each property on your list falls into, so the duty line in your budget is a real number instead of an allowance you guessed at.
The $10,000 grant
The First Home Owner Grant is for new homes only. An established house never qualifies, whatever it cost or however recently it was renovated. If a new build is on your list we confirm the grant before you sign a contract, because it is worth more to you than a first year of chipping away at the balance.
What The 5% Deposit Scheme Means For Your Deposit
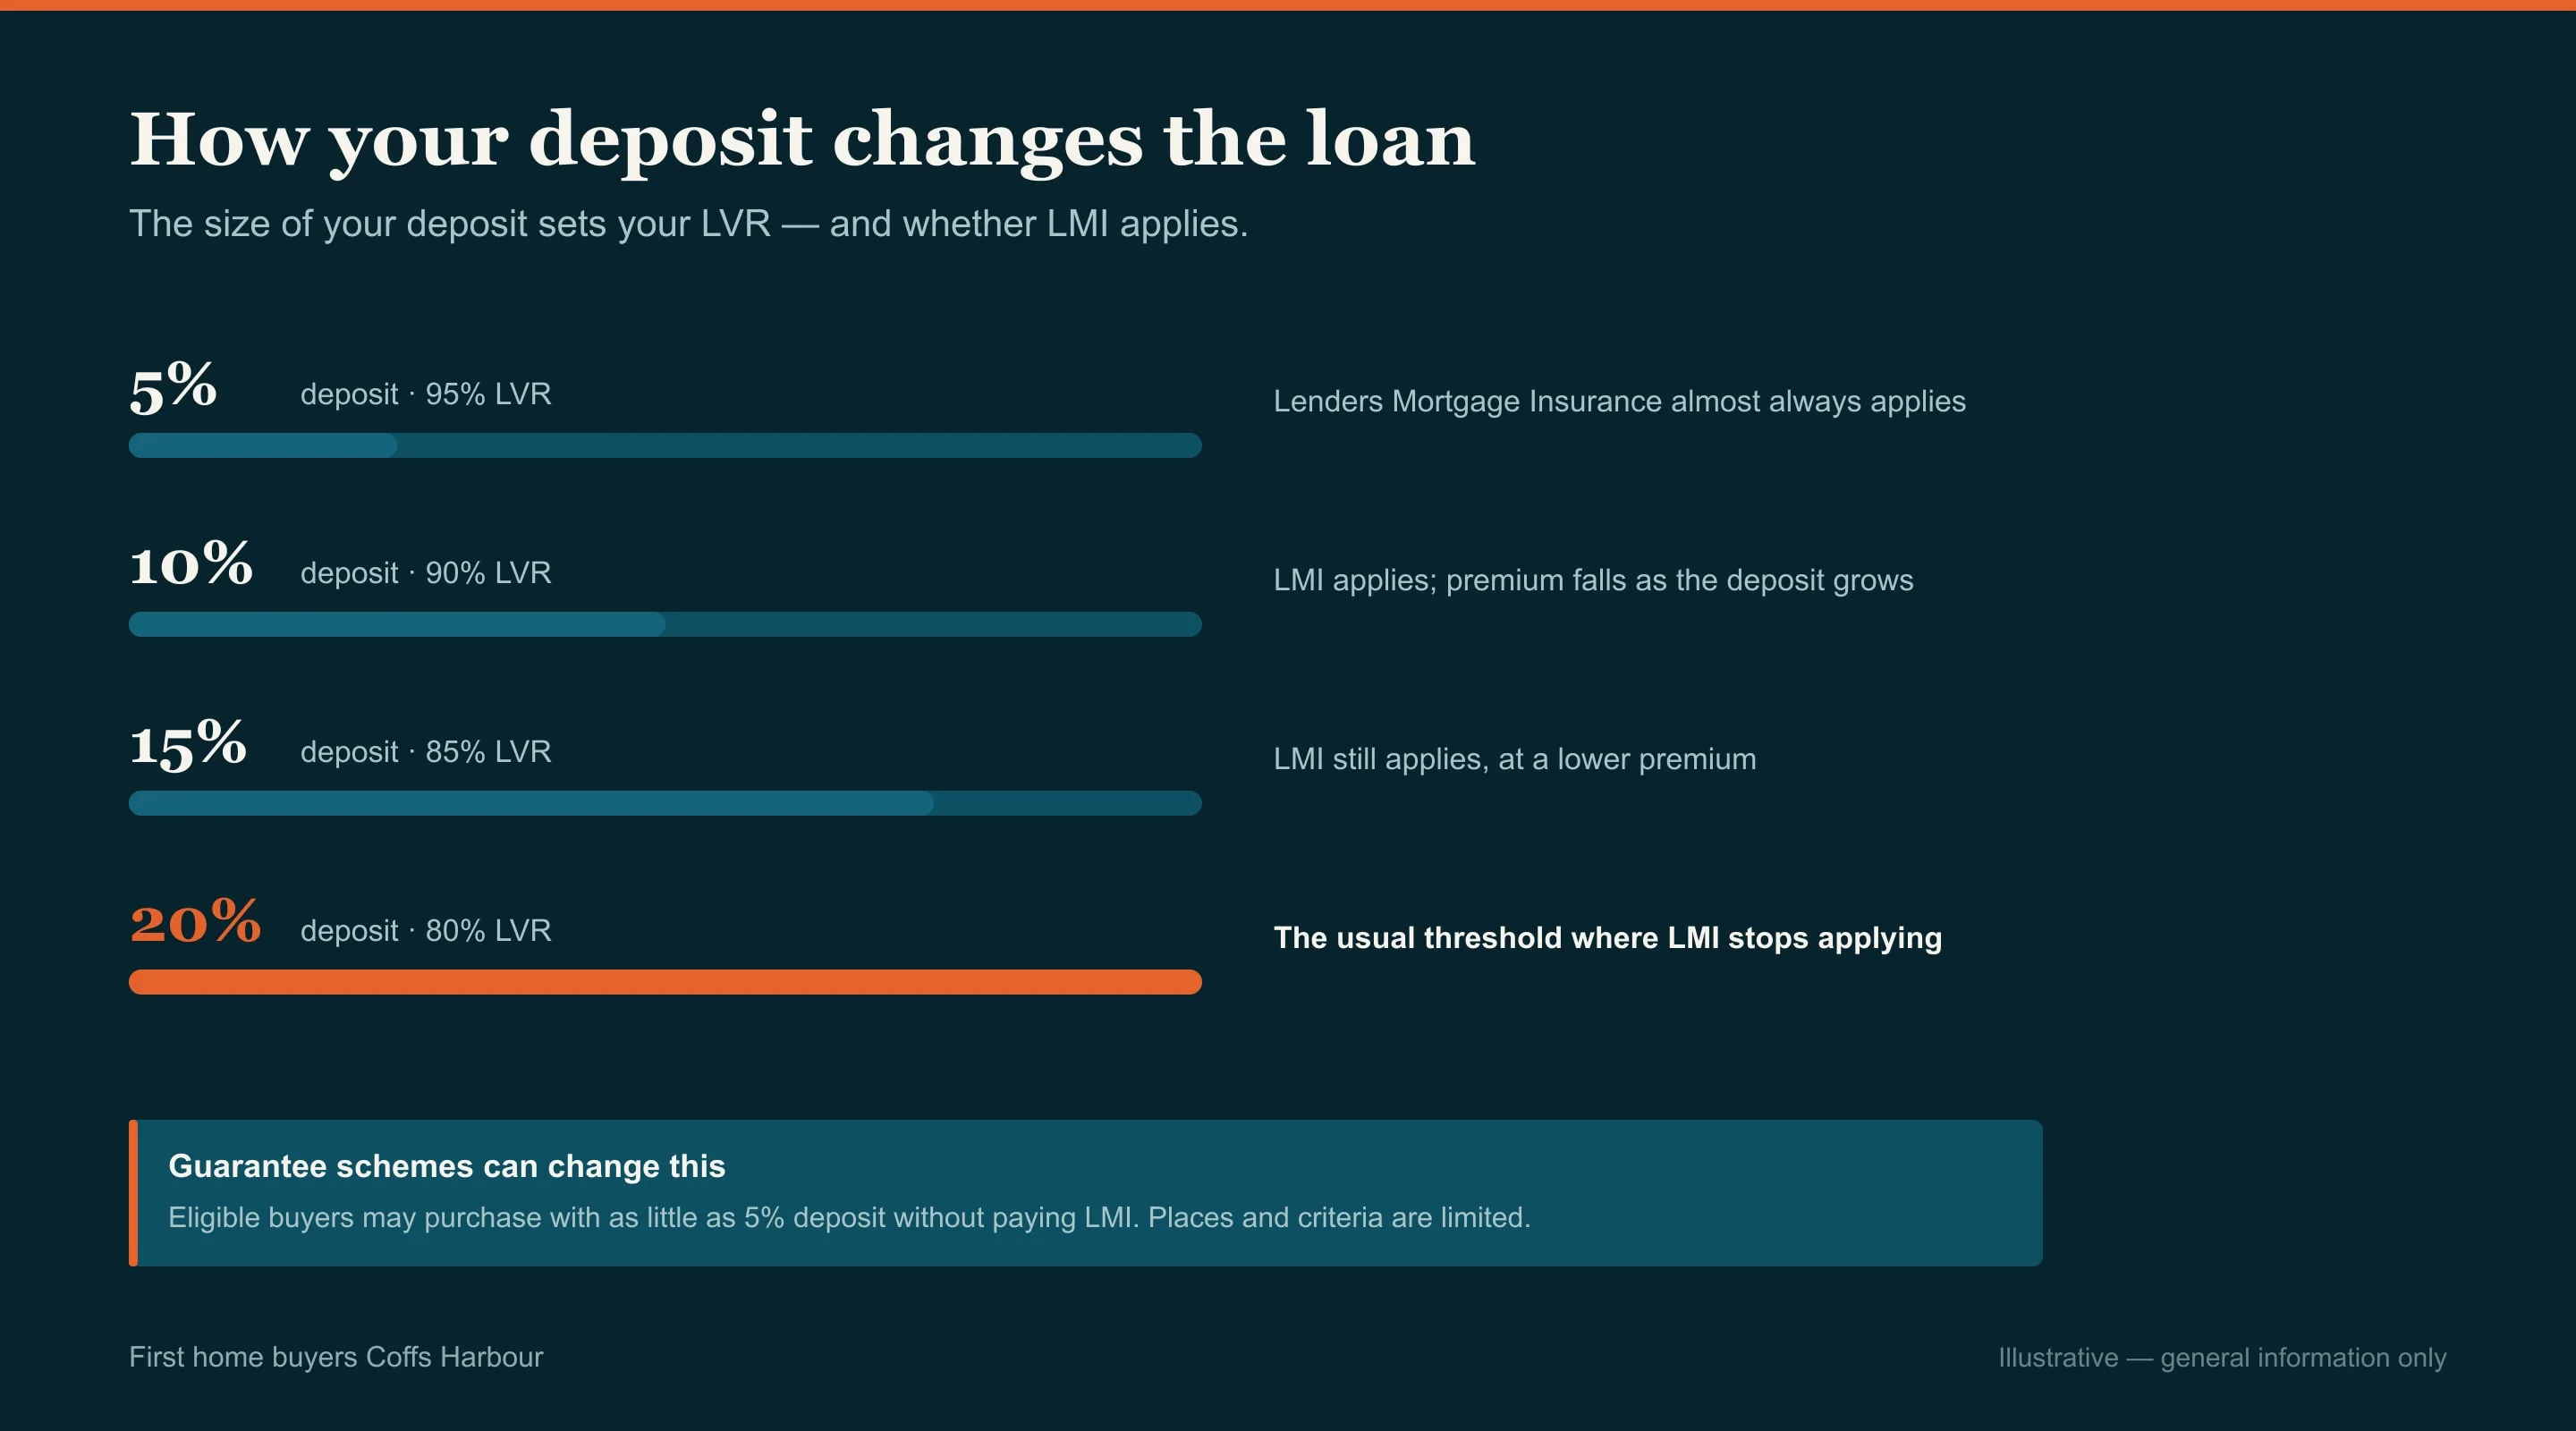
The scheme moves two numbers at once: how long you have to save while Coffs Harbour prices move, and whether you pay lenders mortgage insurance. Under it you buy with a 5% deposit and no insurance premium is charged, because the government guarantees the gap instead.
Outside the scheme, borrowing above 80% of the property value normally triggers that premium, and it is capitalised into your loan rather than paid up front. We run both versions for you, so you can weigh what saving to 20% actually buys against what the market does to prices while you save.
Buy now with 5%, or save to 20%
What this turns on is not the deposit at all. It is whether your income supports the larger loan at the assessment rate. We test that first, because if the borrowing power is not there the deposit question is academic.
Genuine savings still matter to every lender on the Coffs Harbour panel. They want to see the deposit accumulated over time rather than appearing in a single line. If yours came from a gift or a sale, say so early: it narrows the lender list rather than ending the conversation, and it is much easier to work around before lodgement than after.
Property price cap that applies here
$1,500,000
Coffs Harbour-Grafton is a designated NSW regional centre, so the higher cap applies rather than the rest-of-state figure. Both the purchase price and the lender’s valuation have to sit at or under it.
firsthomebuyers.gov.au Fact Sheet, effective 1 October 2025
Which Of The Three You Can Stack
You can hold the federal deposit scheme, the NSW duty exemption and the grant at the same time where you meet each set of conditions. The one combination that is closed is the 5% Deposit Scheme alongside Help to Buy shared equity, so you pick one. We model both and tell you which leaves you better off.
| Scheme | What it does for you | The threshold to watch |
|---|---|---|
| 5% Deposit Scheme (federal) | Buy with a 5% deposit and no mortgage insurance premium | $1,500,000 price cap, the regional centre figure |
| First Home Buyers Assistance Scheme (NSW) | Removes or reduces your transfer duty | Full exemption to $800,000, tapering to nil at $1,000,000 |
| First Home Owner Grant (NSW) | $10,000 toward a new home | New homes only, so an established house never qualifies |
The residence condition on all three
Every one of them carries a residence condition, so the Coffs Harbour place has to be the one you live in. On contracts dated from 1 July 2023 you have to move in within 12 months of settlement and live there continuously for 12 months. If the plan is to rent it out first, tell us now. It changes which scheme you should be using, and reworking the structure is a great deal easier than breaching a condition.
Getting Your First Home Loan Approved in Coffs Harbour
Approval is where the schemes stop mattering and the assessment starts. Your lender tests your repayments at the rate you would actually pay plus three percentage points, a buffer APRA held steady on 27 November 2025.
That is the usual reason a borrowing figure comes back lower than the calculators suggested. We work at the buffered rate from the first conversation, so the number we give you is the number the lender lands on.
The $1,500,000 cap also sounds more useful than it is. PRD put the median house price here at $950,000 in the first quarter of 2026, and CoreLogic’s February 2026 figure, reported through Your Investment Property, was $830,000. The practical effect is that the cap is almost never the constraint in Coffs Harbour. Your income is.
So we lead with capacity. We work out what you can borrow at the buffered rate, then work backwards to a shortlist that clears both the cap and your repayments.
Asked and answered
First Home Buyer Questions
Does the $1,500,000 cap really apply here?
Yes. Coffs Harbour and Grafton are designated together as a regional centre, which puts the whole area on the higher cap rather than the rest of state figure. Caps are set by postcode, so we confirm your exact postcode in Housing Australia’s tool before you rely on it.
Can I get the $10,000 grant on an existing house?
No. The First Home Owner Grant is new homes only, and no established house qualifies regardless of price or condition. If the grant matters to your budget, new builds and house and land are the places to look, and we tell you what that changes about the finance before you switch your search.
Can I use more than one scheme at once?
Usually yes. The federal deposit scheme, the NSW duty exemption and the grant can stack wherever you meet each set of conditions. The exception is the 5% Deposit Scheme and Help to Buy shared equity, which cannot be held together, so we work out which of the two leaves you better off.
What income do I need to qualify?
There is no income cap on the federal scheme any more; that went on 1 October 2025. Your lender still has to be satisfied you can repay, assessed at your rate plus three percentage points. Income therefore decides the size of your loan rather than your eligibility for the scheme.
Who you deal with
Talking To Us About Your First Home
The person who answers your first call is the person who packages your file, lodges it and rings the lender when the valuation is late. Nothing gets handed to a processing team, so you never have to explain your deposit twice.
We work across Coffs Harbour, the beaches either side of it and the hinterland behind, and most of it happens by phone and email because that suits you better are at work. If you would rather sit down with the contract in front of you, that is easy to arrange.
- What it costs to ask
- Nothing. Checking your scheme eligibility is free, and the lender pays us on settlement.
Where to start
Start With The Eligibility Question
Which schemes you can use decides which listings in Coffs Harbour are worth your time, so it is the sensible thing to settle first. Call us, or use the form and tell us roughly where you are up to.