Movers and upgraders
Home Loans Coffs Harbour
We arrange home loans Coffs Harbour movers and upgraders use to buy their next place, and the work starts with a borrowing figure you can rely on rather than a calculator estimate.
Your second or third purchase is a different problem from your first. There is equity to work with, an existing loan to deal with, and a settlement date that has to line up with someone else’s.
- Borrowing power worked out at the assessed rate
- A pre-approval a credit officer has actually signed
- Your existing loan and your equity handled together
Get a borrowing figure
What you earn, what you owe, and roughly what your current place is worth.
What We Do For Your Next Purchase
We calculate what you can borrow against your income and your existing commitments, compare the lenders whose policy actually fits your file, and get you a pre-approval that has been through a credit assessor. Then we hold the lender end of the purchase: the valuation, the conditions, the paperwork your conveyancer needs, and the settlement booking.
It suits you if you already own in Coffs Harbour and are moving up, moving out or moving across, and you want to know your number before an agent asks for it. Most of our clients get in touch at the point where they have started looking on weekends and realised they cannot answer that question.
The borrowing power work costs you nothing, and you can have that conversation more than once as your plans change. The lender pays us a commission when a loan settles, so nothing before that point is billed to you, including the answer that you are better off waiting.
If this is your first purchase, or the money will come out of a business rather than a payslip, the assessment runs differently enough that it is a separate conversation. Say so on the first call and we will start in the right place.
Step by step
How We Run Your Application
Five stages, and you hear from us at each one whether or not there is anything new to report.
-
Fact find
Twenty minutes. Income, debts, equity and what you are trying to buy. No documents needed at this point.
-
Borrowing power
A day or so. We calculate what you can borrow at the buffered rate across the lenders whose policy fits, and show you where they diverge.
-
Pre-approval
Typically one to two weeks. Documents collected, file packaged, lodged for a full credit assessment rather than a system decision.
-
Offer support
While you are bidding. We sanity check the price against the likely valuation and confirm what the lender wants if your offer is accepted.
-
Formal approval and settlement
Commonly four to six weeks from contract. We manage the valuation, clear the conditions and book settlement with your conveyancer.
What to have ready
- Payslips and a year to date summary for every applicant
- Three months of statements for your everyday account
- Loan and credit card statements showing the limits
- The rates notice and current loan statement for the property you own
First questions
What Buyers Ask Before They Call
What does this cost me?
Nothing on a standard residential loan. Brokers here are paid a commission by the lender when the loan settles, which is why the borrowing power conversation is free and why you can have it more than once as your plans change. Any fee that could apply would be put in front of you in writing, with the amount on it, before you committed to anything.
How soon can I start making offers?
As soon as you have a pre-approval, which is commonly one to two weeks from the point we have your documents. You can start looking well before that, and plenty of people do, but an agent in Coffs Harbour will treat your offer differently once there is an assessed approval sitting behind it.
What do you need from me to start?
Your income, your debts with their limits, and a rough idea of what your equity looks like. That is enough for a borrowing figure. We do not ask for a single document until you have decided to proceed.
Getting Pre-Approved in Coffs Harbour
Two different things are sold under the name pre-approval in Coffs Harbour, and only one of them is worth having. Some bank pre-approvals are generated by a system against the numbers you typed in, with no human assessment behind them at all. They fall over at the worst possible moment, which is after your offer has been accepted.
What we arrange is a fully assessed pre-approval: documents supplied, income verified, a credit officer’s decision recorded against your file. It is not a guarantee, because the property still has to value up, but the part that depends on you is settled before you start bidding.
That counts for more in a market where stock moves quickly. CoreLogic’s February 2026 figures had houses in Coffs Harbour selling in around 42 days and units in around 46. An agent will take a properly assessed buyer over a faster one holding a system printout, and we give you something you can put in front of them.
How Much You Can Borrow in Coffs Harbour
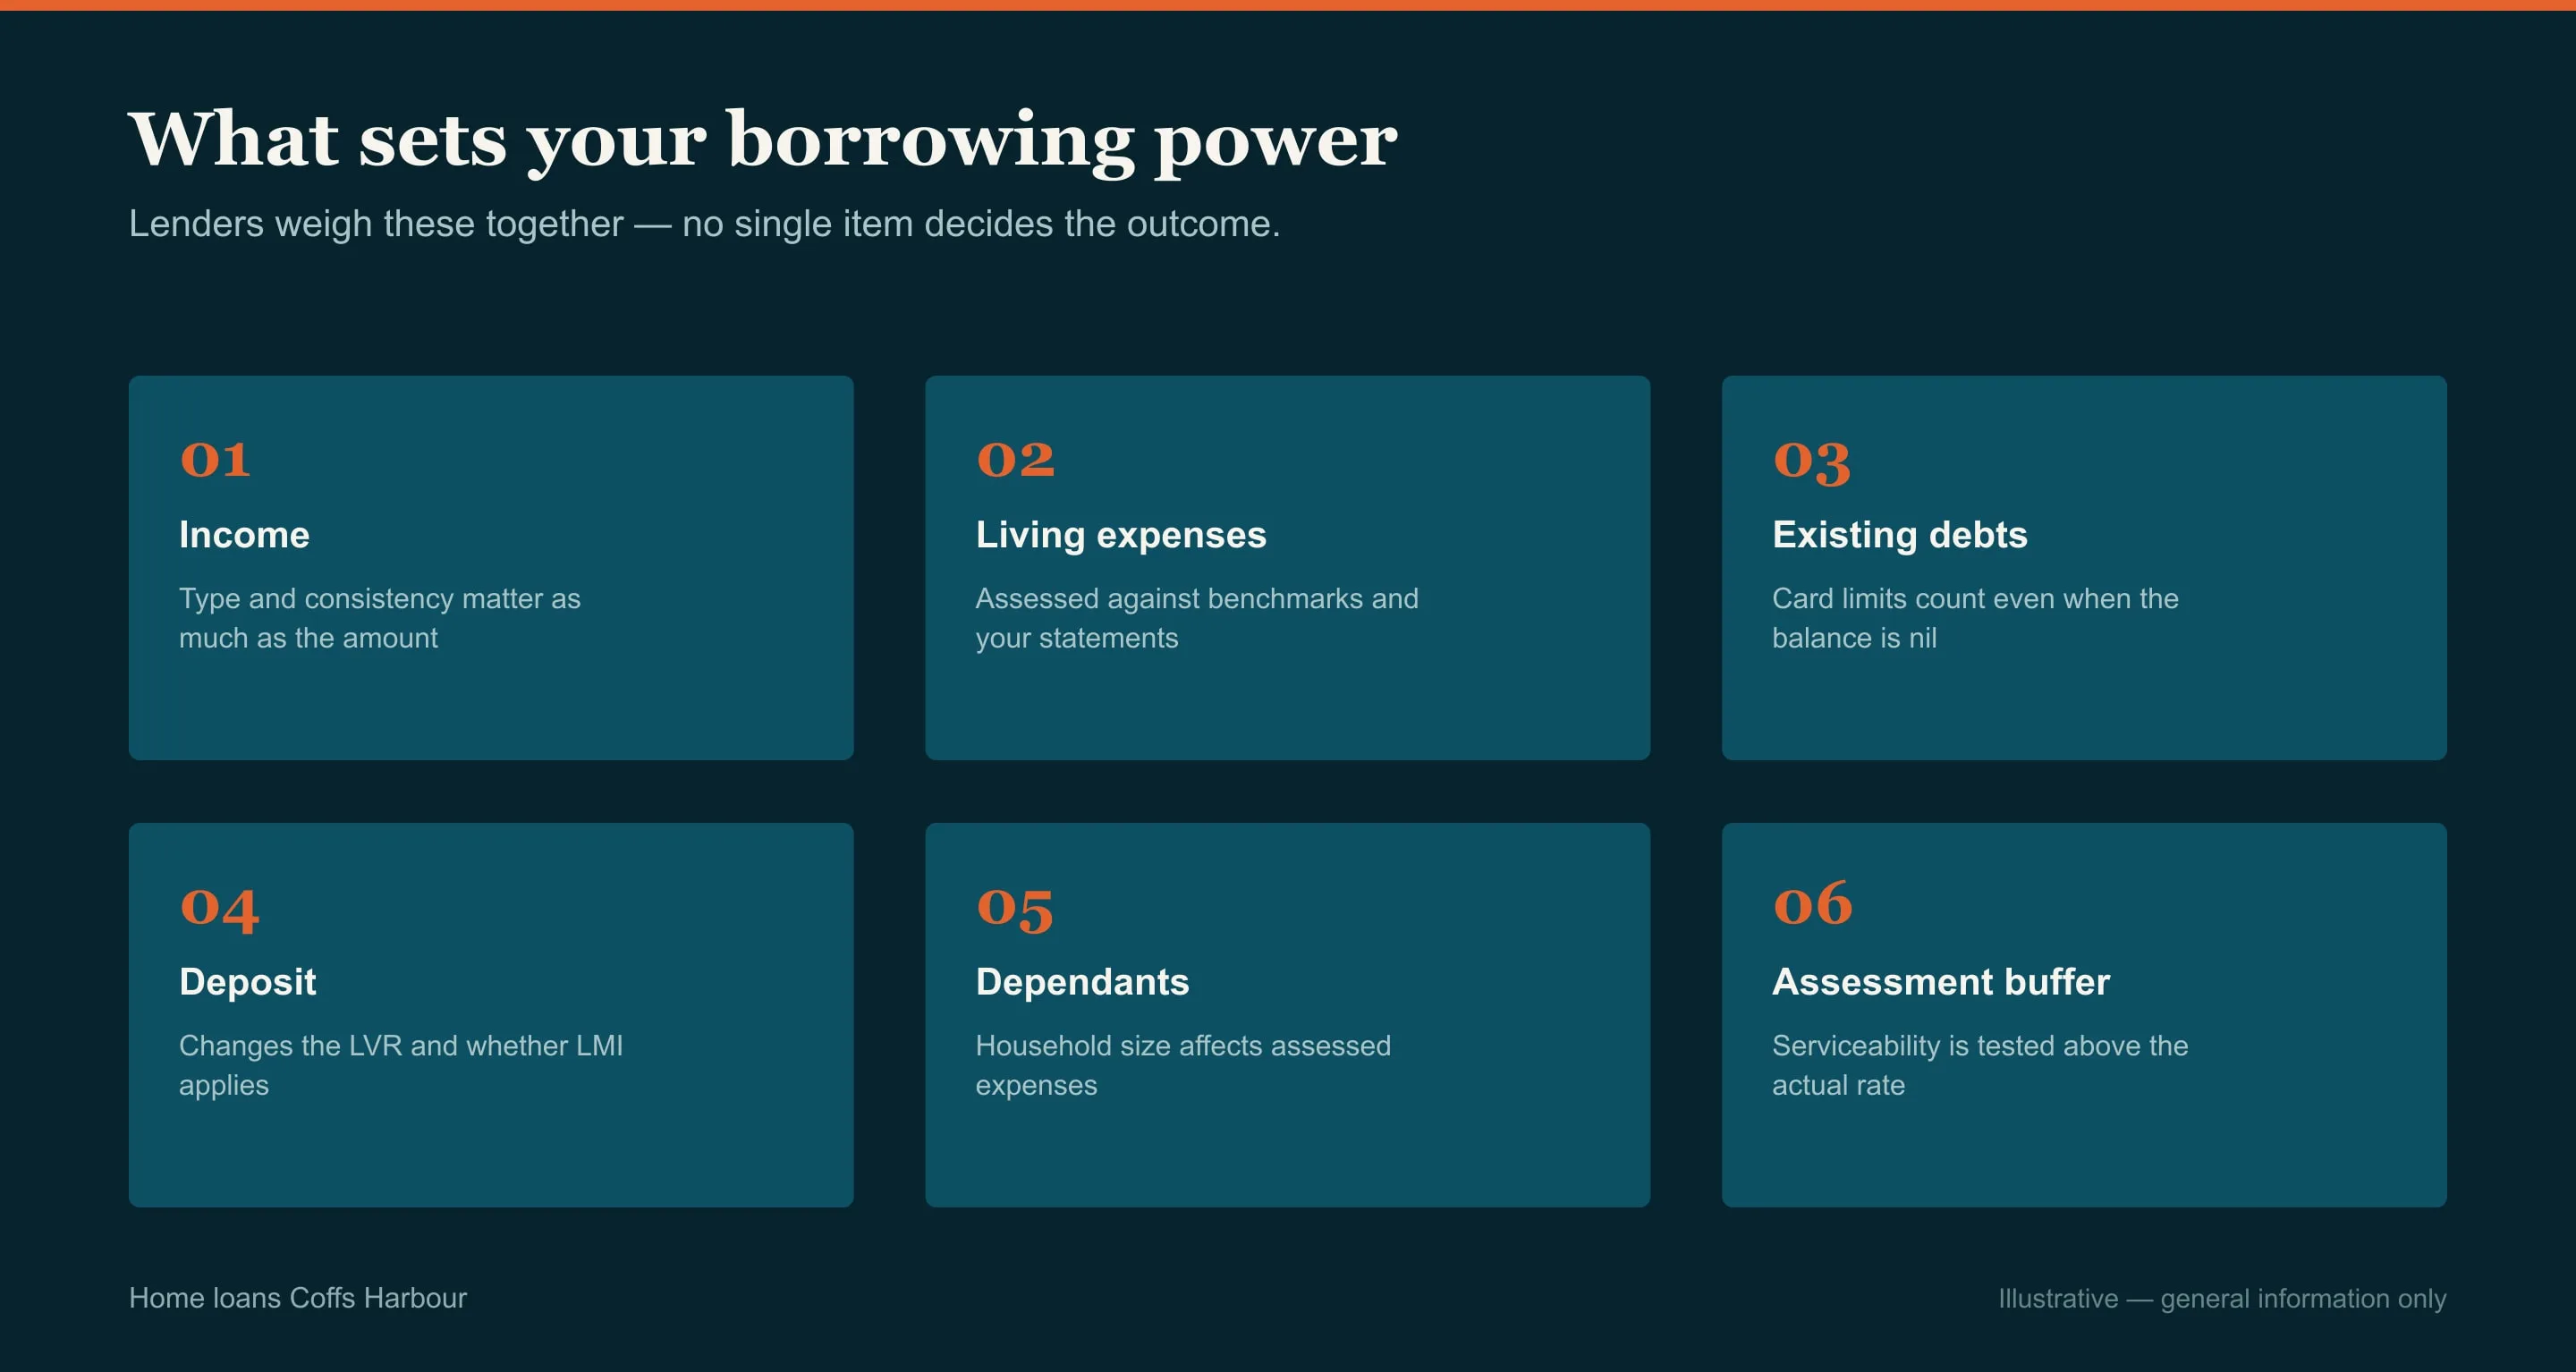
Your lender assesses your repayments at the rate you would pay plus three percentage points. Every Coffs Harbour lender applies it, on every application, and it is why our figure comes in below what a bank’s marketing calculator suggested. We work at the buffered rate from the start so nothing moves underneath you later.
Your declared expenses have a floor
Lenders apply the Household Expenditure Measure as a minimum on your living costs. If what you declare comes in under the benchmark for your Coffs Harbour household size, income and postcode, the benchmark gets used instead. It is a floor rather than an estimate of your actual budget, so there is no advantage in understating what you spend. It simply gets replaced.
What does help is clearing out what sits above the floor. We go through your commitments with you before lodgement and tell you which ones are worth dealing with first, and roughly what each one is worth in borrowing power.
Credit cards are counted at the limit
A card with a $15,000 limit and nothing owing on it is still assessed as though you could draw the lot tomorrow. Every Coffs Harbour lender applies a monthly repayment against the limit, not the balance. Cutting or closing an unused card is often the single fastest way to lift what you can borrow, and we tell you what it is worth before you make the call.
Added before a lender tests your repayments
3 percentage points
Your application is assessed at the rate you would pay plus three points, not at the rate itself. It is the single biggest reason a borrowing estimate comes back lower than people expect.
APRA, buffer held at three points, 27 November 2025
What Documents To Have Ready
None of this is needed for a borrowing figure. It is needed to lodge. Getting it together early is what turns a two week pre-approval into a one week one, which matters when Coffs Harbour stock moves as quickly as it does.
- Your last two payslips each, and a year to date figure if your pay varies
- Three months of transaction statements for your everyday account
- Statements for every loan and credit card, showing limits and current balances
- Your latest rates notice and loan statement for the home you already own
- Photo ID for each applicant
If any of your income is bonus, commission, overtime or rent, flag it early. Lenders shade each of those differently, and which one you lean on can decide where we lodge.
Choosing Your Loan Structure
The structure decides how the loan behaves for the next few years, and it is far easier to get right at the start than to change afterwards. We set your Coffs Harbour loan up around what you are actually planning to do, rather than around a default.
Fixed, variable or split
Fixing buys certainty and costs flexibility: extra repayments are usually capped, and breaking the term carries a cost that depends on where rates have moved. Variable does the reverse. A split does some of each. If you expect a lump sum, or think you might sell inside the term, we weight it accordingly.
Offset or redraw
An offset is a transaction account whose balance reduces the interest charged on your loan while the money stays yours. Redraw is money you have already repaid, and the lender can restrict access to it. If you are holding a cash buffer, or may one day turn this home into an investment, the difference matters and we walk you through why before you pick.
Buying before you sell
If the next purchase has to happen before your current home settles, that is a different structure and a different conversation. Raise it on the first call so the pre-approval gets built in the right shape from the start.
Asked and answered
Questions About Your Next Home Loan
What makes a pre-approval a real one?
A credit officer has seen your documents and made a decision on them. A system pre-approval has only seen the numbers you typed into a form. The difference does not show up until your offer is accepted, which is the worst possible time to find out about it.
How long does approval take?
Pre-approval is commonly one to two weeks once we have your documents. Formal approval after you hold a contract is usually faster, and settlement is typically four to six weeks from exchange. Valuations and outstanding conditions are what stretch any of it.
Should I sell first or buy first?
Selling first is cheaper and calmer, but it can leave you renting or moving twice. Buying first needs bridging finance and a realistic view of what your current home will fetch. We run both and show you what each one costs before you commit either way.
Will my credit card limits really hold me back?
Often more than the balance on them does. Every lender assesses a card at its limit, so an untouched $20,000 of available credit is treated as a monthly repayment you are already making. We quantify it for your file and tell you whether it is worth acting on before we lodge.
Who you deal with
Who Handles Your Loan
One broker runs your file from the first phone call to settlement. That means the person chasing your valuer is the person who knows why your bonus income matters, which is the difference between a week of back and forth and a phone call.
We are based in Coffs Harbour and work across the coast and the hinterland, and we will happily take the first conversation at seven in the evening if that is when you are free.
- What it costs to ask
- Nothing. Working out what you can borrow is free, and the lender pays us on settlement.
Where to start
Find Out What You Can Actually Borrow
A real borrowing figure, tested at the assessment rate, changes what you look at and what you offer. Call us, or use the form with your income, your debts and what your current place is worth.